

Is The Phone Number To Hampton Township Fire Department
My wife and I discovered the Fire movement nearly 3 years agone. We've always been decent budgeters, savers, etc., just three years ago was when it really clicked for us… "We can retire early on!"
It all came downwardly to u.s.a. figuring out our "FI number" and realizing information technology was reachable in our 40s.
Why the 4% Rule for Retirement Doesn't Always Work
Well-nigh Burn enthusiasts follow the 4% rule of thumb to figure out how much money they volition need for retirement. It'southward pretty elementary, yous just take your almanac expenses, multiply them by 25, and there you have information technology — that's your FI number.
That's a great rule when you're offset starting out, only as you grow older and life throws you more than changes, you realize that your FI number is actually a moving target . Information technology changes as your future expenses change.
The reason my wife and I don't accept an verbal FI number is because nosotros don't know what our verbal future expenses are gonna exist. There are too many variables. And not just small variables, Big ones, like:
- We currently don't ain a home. We've accounted for rent, but this number could modify drastically.
- We don't know which city we'll live in. Heck, we don't fifty-fifty know which country nosotros'll live in.
- Health care costs are a huge unknown.
- We don't take kids yet. No clue how much they will price.
Each of these expense variables has a 25x touch on how much we demand to salvage for comfortable retirement. So, instead of shooting for an exact magic number, my wife and I are more often than not shooting for a "range."
Here are our thoughts and some rough calculations…
Figuring Out Our FI Number: Constants and Variables
Earlier jumping into what we don't know, here'south some of our living expenses nosotros kinda do know. These are annual expenses based on what nosotros reckon will be a fairly comfortable lifestyle for the states.
Food: $6,000
Booze: $3,000
Internet: $840
Phones: $1,200
Cars: $two,400
Gifts/Charity: $5,000
Pets: $ii,000
Amusement: $1,200
Travel: $v,000
Miscellaneous: $2,400
TOTAL: $29,040
I'1000 a round numbers guy, and then let's just call this $30,000 per year in fixed and abiding living expenses. (Yes, this number volition increment with aggrandizement twelvemonth after year. At this point, all I care about is Year 1 numbers in retirement.)
$30k x 25 = $750k needed in retirement funds to cover these expenses.
OK, then now nosotros have to add in 3 x variables… Housing, health intendance, kids.
Housing and Future Hire Guesstimates
Since my married woman and I aren't prepare to buy a business firm, we'll include monthly hire in our living expenses. This is where ranges come up in, depending on the city nosotros want to live in and size of our house.
Depression estimate: In Los Angeles, we tin happily hire a 1 bedroom flat in a good area for ~$2,500 per month. (We pay less than this now thank you to a sweetheart bargain, but that won't concluding forever.) So, total annual would exist $30,000 as a safe bet.
High gauge: I don't think we'll ever alive in a McMansion, only if we need an extra sleeping room and wanna exist in a skillful schoolhouse commune or something, let'due south say information technology'll be $4,000 per month to rent a identify. That's $48,000 annual in rent on the high end.
Depression hire: $30k x 25 = $750k needed in retirement
Loftier rent: $48k 10 25 = $1.2 million needed
If we get the warm and fuzzies and want to buy a domicile somewhere, as long every bit the monthly payments and expenses are less than $4k for housing, we're covered.
Health Insurance and Health Care Variables
This one is the toughest for early retirees to figure out. Terminal year we had an awesome mail from the Dragons On FIRE most healthcare in early retirement , which is a pretty thorough guide to trying to work out future healthcare costs.
Complimentary selection: For my married woman and I, if we end up moving dorsum to Australia, we could potentially get past paying $0 for healthcare . 100% of Australian full time residents take Medicare, and pay cipher for hospitals and doctors appointments. (Private health insurance is also an option, and apparently the average cost is simply $2000 per twelvemonth per person!)
"Cheap" Healthcare: Terminal yr I spent some time evaluating health insurance vs. having no insurance and paying out of pocket for intendance. My wife and I skated by for virtually iii years without insurance, merely paying ~$4k during that unabridged time ($3k of which was government fines). Per the "national boilerplate" for u.s., our costs apparently would exist almost $iv,000 per yr (including fines).
Anyway, I know many of you lot are going to disagree with this, but I'one thousand gonna use $10k per year as our low almanac guess. This would comprehend either a basic high deductible health programme (HDHP) premium with depression care use, or living without insurance and paying $10k out of pocket per year for fixes.
Loftier healthcare budget: Also in last year's post I calculated a HDHP insurance programme for my wife and I and worked out that it would toll a max of $20,400 per yr . This covers all premiums for the policy as well as maxing out the family deductible every unmarried year.
Low healthcare: $10k x 25 = $250,000 needed in retirement
High healthcare: $xx.4k = $510,000 needed in retirement
Future Kids Cost
Quick update on our foster/adopt process: We've completed all the pre-approval Zoom classes and almost of the onboarding homework. A social worker came and did 1 dwelling house inspection and so far, and we've got a few more than inspections, also as interviews and more qualifying stuff to become through. All in all, I'd say nosotros're fifty% of the manner through the county approval process.
If we determine non to accept kids: And so our cost is $0 and it doesn't actually affect our Burn number at all.
Boilerplate cost of raising a kid in the U.S.: Based on 2019 numbers, the average total cost that middle-income parents will spend on a child from age 0 – eighteen is $284,570. If my wife and I adopt a kid, I can safely say our expenses will be lower than this, considering the state provides costless healthcare, a small monthly stipend per child, a TON of support for teaching services and stuff like that. For our estimate purposes, I'k gonna go with an annual cost of $12,000 per child.
Cost for one kid: $12k 10 25 = $300k
Cost for 2 kids: $24k ten 25 = $600k
Alright, let'due south add this all upwardly…
Annual Expense Totals and FI Number Range:
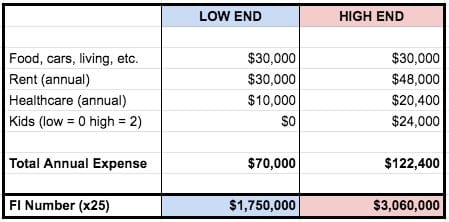
On the depression stop, information technology looks like we would demand $ane.75 million in assets for retirement. We'd live in a modest rental, have no kids, 1 domestic dog, have subsidized or cheap health intendance, and do all the regular living stuff we savour doing today.
On the high end, nosotros would need just over $3 million invested. Nosotros'd rent an upscale or bigger habitation, have a couple kids, a dog, max out our healthcare plans every twelvemonth, and still enjoy the modest lifestyle we have today.
That's a pretty huge divergence in FI numbers!
Kind of scary to retrieve almost… the life decisions my wife and I haven't figured out yet could take a $1.3 one thousand thousand touch on how much we demand to save. And information technology might be 5, 10, or more years before nosotros are even ready to make these decisions.
Coast FIRE: Options, Flexibility and the Messy Middle
I know a couple in their early 20s who have their unabridged life mapped out already. They accept a dream house picked out, know exactly how many kids they want, programme to vacation in the same spot each yr, etc.
On the flip side, I know some people in their 60s who nonetheless haven't figured out what they want to be when they grow upwards! Having "plans" makes them feel boxed in, then they never commit to annihilation.
My wife and I are somewhere in the messy middle. We like planning, simply we're also open up to change.
Adopting the Coast Fire mentality ways not only is our retirement timeline up in the air, but our magic FI savings number is uncertain, likewise. Every bit uncomfortable every bit that may seem, my wife and I are confident that if we aim high and proceed trying our all-time, we can handle both deliberate and unexpected changes every bit they come along.
[Read more: Ho-hum down … FIRE is not a race]
Anyway I've been asked a lot recently, "What is your FI number?" … And this is why I don't have a great respond. Somewhere between $2-3 Million? 🤷♂️ As life goes on and things become clearer, you'll all be the starting time to know.
Practise you all have a specific target mapped out? Or are you lot within a broad range, too?
(Visited 12 times, 1 visits today)
Become weblog posts automatically emailed to you!

Is The Phone Number To Hampton Township Fire Department,
Source: https://www.budgetsaresexy.com/why-my-fire-number-keeps-changing/
Posted by: rowleysaidom68.blogspot.com
0 Response to "Is The Phone Number To Hampton Township Fire Department"
Post a Comment